Invoice Factoring vs. Merchant Cash Advance (MCA): Invoice Factoring a Smarter Alternative for Business Funding

An Educational White Paper from AmeriFactors Financial Group. LLC

Executive Summary

Businesses need reliable access to working capital to make payroll, purchase inventory, pay vendors, accept new contracts, and support growth. However, the timing of customer payments does not always match the timing of business expenses. The best financing solution should do more than provide fast cash. It should support the long-term health, stability, and growth of the business.

When cash is needed quickly, many business owners consider a business cash advance, also known as a Merchant Cash Advance (MCA). These financing arrangements are often promoted as fast and easy to obtain, but the long-term effect on cash flow can be significant. Merchant Cash Advances may require daily or weekly withdrawals from a business bank account. They can also carry substantial costs and may create additional financial pressure when revenue slows or customers pay later than expected.

Invoice factoring provides a different approach. Rather than advancing money against future sales, invoice factoring allows a business to access working capital from eligible B2B invoices it has already earned. Funding is tied to outstanding accounts receivable, and the factor receives payment when the customer pays the invoice, not through withdrawals directly from the business account.

This white paper explains:

Why Businesses Need Working Capital

Even successful and growing companies can experience cash flow challenges. A business may complete its work, deliver its products, and issue invoices on time, yet still wait 30, 60, or even 90 days for customers to pay. During that waiting period, the company must continue covering its expenses.

Businesses commonly seek working capital for payroll, inventory, vendor payments, growth, seasonal needs, unexpected expenses, and slow-paying customers.

A cash flow shortage does not necessarily mean a business is struggling. In many cases, the company is growing faster than its available cash can support. The challenge is choosing a funding solution that addresses the immediate need without creating a larger financial problem.

What Is a Merchant Cash Advance and How Do They Work?

A Merchant Cash Advance is a form of revenue-based financing. The business receives a lump sum in exchange for the funder’s right to collect an agreed upon amount from future business sales or revenue. An MCA is generally structured differently from a conventional business loan. Instead of making one monthly payment, the business may be required to make daily or weekly payments through automatic withdrawals from its bank account. MCAs may appeal to companies that need money quickly or do not qualify for conventional financing. However, speed and convenience should be evaluated alongside the cost, payment structure, and effect on future cash flow.

A typical MCA transaction works as follows:

  1. The business applies for funding.
  2. The funder reviews revenue, bank statements, credit score, and sales activity, among other things.
  3. The business receives a lump sum minus closing fee.
  4. The funder establishes a total amount that must be remitted.
  5. Payments are withdrawn daily or weekly.
  6. Withdrawals continue until the agreed amount has been collected.
  7. If the business misses a payment, the total amount will be recalculated to include significant additional fees and penalties.

Cash advances are not fully amortizing loans. Traditional loans reduce your principal balance over time through an amortization schedule that recalculates interest on the remaining principal. MCAs apply a flat multiplier called a “factor rate” to the entire advance in the beginning. The total principal plus the factor amount is owed from day one. Paying off the balance early typically does not reduce the overall cost or recalculate fees.

How Merchant Cash Advances Are Priced

As indicated above, Merchant Cash Advances commonly use a factor rate rather than a traditional interest rate. An MCA “factor rate” is not the same thing as the rate or fee associated with invoice factoring. Despite the similar words, they refer to two very different calculations and financing structures. A factor rate is a multiplier used to calculate the total amount the business is expected to remit. MCA providers commonly quote factor rates such as 1.20x, 1.35x, or 1.40x. For example, a 1.40x factor rate on a $100,000 advance results in a $140,000 total repayment amount, before any additional fees. (See the “Fee and Cashflow” section below for an example.)

Because the factor rate is applied to the original amount, it should not be confused with a conventional annual percentage rate. The repayment period may also be much shorter than a traditional loan, which can make the effective annual cost substantially higher than it first appears. Because MCA factor rates are not traditional interest rates, they may also make it difficult to understand the annualized cost of obtaining and repaying the funds over a relatively short period.

How MCA Payments Can Affect Cash Flow

Many businesses focus on how quickly they will receive the money but underestimate the effect of frequent withdrawals. With a traditional monthly payment, a business has more time to manage incoming and outgoing cash. With an MCA, money may be withdrawn every business day or every week before the company pays its other obligations. Even when the company generates enough revenue to make the payment, the timing can create financial pressure.

An MCA Does Not Eliminate the Underlying Cash Flow Gap

Many businesses accept an MCA because they need immediate cash. While an MCA can provide quick cash, it does not necessarily solve the underlying cash flow problem. Instead, it advances money based on future revenue not even yet earned, and begins collecting payments immediately. If the business is already waiting 30, 60, or 90 days for customers to pay, the MCA withdrawals may begin long before those customer payments arrive. As a result, the company may still face the original cash flow shortage while also managing a new daily or weekly obligation.

Warning Signs Before Accepting an MCA

A reputable provider should be willing to explain the transaction clearly and provide time for review. Business owners should pause and seek professional guidance when they encounter:

Possible Risks of Merchant Cash Advances

Frequent Withdrawals

Daily or weekly payments can reduce financial flexibility and make it more difficult to cover essential expenses.

Short Repayment Period

The obligation may be collected over a relatively short period, placing intense pressure on operating cash. 

High Total Cost

Factor rates and additional fees may make the total cost of the advance significantly higher than expected. If the MCA company does not give you a sample transaction and fee calculation, you should ask for one.

MCA Stacking

When one MCA reduces available cash, a business may take another advance to cover payroll or other expenses. This practice, often called MCA stacking, can result in multiple providers withdrawing money from the same operating account resulting in a much more significant cashflow issue.

Contractual Restrictions

MCA agreements may contain provisions related to UCC Filings, bank account access, remedies upon a default including an automatic judgment against the business, and required changes to business operations.  Business owners should review these terms carefully.

Reduced Access to Future Financing

Existing MCA obligations, frequent withdrawals, or competing liens may make it more difficult to obtain other financing. Multiple MCA obligations can materially reduce a business’s refinancing options and make a successful restructuring or consolidation more difficult.

Aggressive Collection Activity

Some agreements provide significant collection rights if the business defaults or blocks withdrawals. Business owners should review the complete contract and seek qualified professional guidance before signing.

When is a Merchant Cash Advance a Poor Choice?

The Most Important Question

The most important question is not: Can my business get approved?  It is: Will this financing improve the company’s financial position after the funds are received?

What Is Invoice Factoring and How Does it Work?

Invoice factoring is a financial solution that converts eligible unpaid B2B invoices into immediate working capital. Rather than waiting for commercial customers to pay on 30, 60, or 90-day terms, a business can receive an advance against approved invoices.

A typical factoring process works as follows:

  1. The business provides products or services to a commercial customer.
  2. The business issues an invoice.
  3. The invoice is submitted to the factoring company.
  4. The factor verifies and approves the invoice.
  5. The factor provides an advance.
  6. The business’ customer pays the invoice according to its normal terms.
  7. The remaining reserve, less the factoring fee, is released to the business according to the agreement.

Significantly, funding decisions are based on the creditworthiness of the business’s customers and the quality of the invoices not on the underlying financial condition of the business. This can make factoring available to some companies that may not qualify for conventional or MCA financing because of limited operating history, rapid growth, losses or even bankruptcy.

Invoice Factoring vs. Merchant Cash Advances

Although both solutions may provide fast working capital, they operate very differently.

ComparisonMerchant Cash AdvanceInvoice Factoring
Source of FundingFunding is based on anticipated future sales or revenue, which can change or fluctuate.Funding is based on eligible invoices for products or services the business has already delivered.  
Payment StructurePayments will be withdrawn daily or weekly from the business bank account.The factor receives payment when the business’ customer pays the factored invoice, not usually from the business itself.  
Underwriting FocusFocuses on financial information of the business such as revenue, bank deposits, and sales activity.Focuses on the creditworthiness of the business’s commercial customers and the validity of the invoices.  
Effect on Cash FlowFrequent withdrawals reduce the cash available for operations or emergencies.Funding accelerates cash already tied up in accounts receivable and does not typically represent a repayment obligation of the business.  
Ability to Support GrowthThe business may need to apply for another advance when additional cash is needed.Funding is tied to actual sales; available funding may increase as the company generates more eligible invoices (and has increased associated expenses).  
Best-Suited BusinessesMay serve businesses with consistent sales and history and that understand the withdrawal and fee structure.Serves any B2B company that sells products or services to other businesses or government entities on payment terms.  

Fee and Cash Flow Comparison

The primary differences between MCAs and factoring are (1) the fees structure and (2) how each solution interacts with cash flow.

Merchant Cash Advance

As previously indicated, an MCA commonly uses a factor rate to determine the total remittance amount. An MCA factor rate is not the same as the fee or rate used in invoice factoring. It is also not a conventional annual percentage rate. For example, assume a company receives a $100,000 MCA with a factor rate of 1.40x.

$100,000 (advanced) × 1.40 = $140,000.

The business receives $100,000 and is responsible for remitting $140,000, before considering any additional fees. The $40,000 difference represents the cost associated with the advance.

The $140,000 will be repaid by the business directly through automatic bank withdrawals either daily or weekly.

Depending on the agreement, additional costs may include return payment fees, administrative fees, default charges, legal costs, or other contractual amounts. A default or other breach may also trigger acceleration or other remedies that materially increase the amount claimed to be due. Business owners should understand these provisions before signing and should not assume they will be able to continue making the original scheduled payments after a default.

Factoring

Factoring costs usually depend on how long the invoice is outstanding.  They are expressed as a percentage of the face value of the invoice. The minimum fee is usually 1-2% of the face amount of the invoice.  For example, if a business sells a $100,000 invoice, the factor may give the business $80,000 up front. Then, when the factor collects, it will give the business the remaining $20,000 less the factor’s fee. With a minimum fee of 2%, the business would get back and additional $18,000 for a total of $98,000 on a $100,000 invoice (plus administrative fees, such as wire fees). 

$100,000 invoice  - $80,000 (initial advance) - $18,000 (paid upon collection) = $2,000 factor fee.

In this example, the business receives $98,000 (total). The $2,000 difference represents the cost associated with the advance. Like a factor rate, a factor fee should not be confused with a conventional annual percentage rate.

The $100,000 will be repaid by the businesses’ customer directly so long as there is no dispute concerning the underlying goods or services provided. As an added benefit, many factors provide help with back-office functions such as delivery of invoices and assistance with collections.

Risk Comparison

No financing product is without obligations. The important question is whether the structure aligns with the business’s revenue cycle and long-term needs.

Merchant Cash Advance Considerations

Invoice Factoring Considerations

Recourse vs. Non-Recourse Factoring

Factoring agreements may be structured as recourse or non-recourse.

AmeriFactors specializes in non-recourse invoice factoring designed to help qualified B2B companies improve cash flow while reducing defined customer insolvency risks.

Frequently Asked Questions

Is a Merchant Cash Advance a Loan?

An MCA is commonly structured as the purchase of a portion of future sales or revenue rather than as a conventional loan. Legal and accounting treatment can vary depending on the agreement and applicable law or regulations.

Is Invoice Factoring a Loan?

From the factor’s perspective, an invoice purchase is generally viewed as an obligation of the business’ customer and not the business itself, particularly if the factoring agreement is non-recourse. However, there are exceptions, and legal and accounting treatment can vary depending on the agreement and applicable law or regulations.

Is Invoice Factoring Better Than an MCA?

Factoring is usually a better fit when a B2B company has eligible unpaid invoices and the primary problem is waiting for customers to pay.

Can a Business Use Factoring With Challenged Credit Including Bankruptcy?

Yes. Factoring decisions focus significantly on customer credit and invoice quality, although all applications remain subject to approval.

How AmeriFactors Helps Businesses Improve Cash Flow

AmeriFactors Financial Group has provided accounts receivable factoring solutions since 1990.

We help B2B companies turn approved invoices into working capital rather than waiting 30, 60, or 90 days for customer payments. Depending on approval, invoice verification, and funding conditions, AmeriFactors can provide funding in as little as four hours after an approved invoice is submitted.

AmeriFactors offers:

As a subsidiary of Gulf Coast Bank & Trust Company, AmeriFactors is also part of a broader financial organization with access to complementary business financing resources. Depending on a company’s qualifications, needs, and intended use of funds, other options may be available through affiliated companies, banking relationships, or trusted lending partners.

Conclusion: Choose Funding That Supports the Business

Merchant Cash Advances can provide fast access to money, but the speed of funding should be weighed against the total cost, fees payment frequency, contractual obligations, and effect on future cash flow and whether the chosen solution is a sustainable solution to the cashflow issue.

For B2B companies with money tied up in unpaid invoices, invoice factoring may provide a more sustainable path to working capital. Instead of advancing money against uncertain future sales, factoring allows the business to access cash from work it has already completed.

Explore Your Working Capital Options

Before accepting a Merchant Cash Advance, speak with AmeriFactors to determine whether your outstanding B2B invoices or another complementary financing solution may provide a better path forward. Call 800-884-3863 or visit amerifactors.com to request a free factoring quote.

Terms and conditions apply. Services offered by AmeriFactors® Financial Group, LLC

Important Notice: The information provided in this article is for general informational purposes only and should not be considered accounting, tax, legal, or financial advice. Businesses should consult with their CPA, attorney, or other qualified professional regarding their specific circumstances and the appropriate accounting, tax, legal, or financial treatment.
How to Improve Cash Flow Without Taking on More Debt: Why More Businesses Use Invoice Factoring Instead of Traditional Loans

Strong Sales Don't Always Mean Strong Cash Flow

Many successful businesses have one thing in common, they're profitable, but they're waiting to get paid. If your customers pay on 30, 60, or even 90-day payment terms, your business may constantly feel like it's running behind, even while sales continue to grow. Payroll, inventory purchases, supplier invoices, insurance, taxes, and operating expenses all need to be paid long before your customers' checks arrive.

For many business owners, the first thought is to apply for another loan or increase an existing line of credit. While traditional financing can be appropriate in some situations, it also adds debt, monthly payments, and often requires strong financial statements and collateral. Fortunately, there's another option for companies with business-to-business (B2B) customers; invoice factoring provides a way to improve cash flow by unlocking money already earned, without taking on additional traditional debt.

AmeriFactors’ non-recourse invoice factoring is not a traditional loan. Rather than lending money that your business repays through scheduled loan payments, AmeriFactors advances funds against eligible accounts receivable and collects payment directly from your customer. With non-recourse factoring, AmeriFactors also assumes the credit risk if an approved customer is unable to pay due to insolvency. This allows your business to improve cash flow without adding a traditional loan and while gaining an additional layer of protection against qualified customer credit risk.

What Is Invoice Factoring?

Invoice factoring is a funding solution that converts your unpaid customer invoices into available working capital. Instead of waiting weeks or months for customers to pay, a factoring company advances funds on approved invoices, allowing your business to access cash much sooner. Because funding is based primarily on the creditworthiness of your customers and the quality of your receivables, invoice factoring can often provide flexibility that traditional lending may not.

Why Businesses Choose Invoice Factoring Instead of More Debt

One of the biggest advantages of invoice factoring is that it addresses the real problem many growing businesses face, not a lack of sales, but a lack of available cash while waiting for customer payments. Instead of adding another loan payment to your monthly obligations, invoice factoring helps convert existing assets, your outstanding invoices, into working capital. Rather than slowing growth because of delayed customer payments, businesses can continue moving forward.

This allows businesses to:

Invoice Factoring vs. Traditional Business Loans

Although both provide access to capital, they solve cash flow challenges differently.

Invoice FactoringTraditional Business Loan
Converts unpaid invoices into working capitalCreates new debt
Funding based primarily on customer creditworthinessHeavy focus on business credit, financials, and collateral
Cash flow grows alongside salesFixed loan amount
No traditional monthly loan paymentMonthly principal and interest payments
Designed to improve working capitalAdds liabilities to the balance sheet

When Does Invoice Factoring Make Sense?

Many businesses discover that cash flow, not profitability, is what's limiting their growth. Rather than slowing growth because of delayed customer payments, businesses can continue moving forward.

Invoice factoring can be an excellent solution for businesses that:

How Invoice Factoring Works

The funding process is straightforward. First, you complete an application, and AmeriFactors reviews the creditworthiness of your customers along with some basic information about your company. Once approved, you sign an agreement and submit eligible invoices for completed work or delivered goods. After confirming the underlying transaction, AmeriFactors advances percentage of the eligible invoice amount. AmeriFactors then collects payment directly from your customer. After your customer pays, AmeriFactors will send you the remaining invoice amount, less our fees.

More Than Funding - A Financial Partner

At AmeriFactors, invoice factoring is about more than advancing funds. We work as an extension of your business by helping improve the efficiency of your accounts receivable process while providing dependable access to working capital. Our goal is to help businesses spend less time worrying about cash flow and more time focused on growth.

Clients also benefit from services such as:

Why Businesses Choose AmeriFactors

For more than 35 years, AmeriFactors has helped businesses across nearly every industry improve cash flow through accounts receivable financing. As part of Gulf Coast Bank & Trust Company, we combine the flexibility of a specialized factoring company with the financial strength and security of an established banking organization. Through our affiliated companies, clients also have access to financing solutions when another option may be a better fit for their business.

Businesses choose AmeriFactors because we offer:

Frequently Asked Questions

Is invoice factoring a loan?

No. Invoice factoring is not a traditional business loan. Instead of borrowing money, businesses convert eligible unpaid invoices into immediate working capital, improving cash flow without creating a conventional loan obligation.

Can invoice factoring help businesses with poor credit?

Yes. Because approval is based primarily on the strength and creditworthiness of your customers and receivables, many businesses that may not qualify for traditional financing can still benefit from invoice factoring.

How quickly can invoice factoring improve cash flow?

Once approved, businesses can often receive funding within hours after submitting approved invoices, allowing them to access working capital much faster than waiting for customer payments or traditional loan funding.

Does invoice factoring work for every business?

Invoice factoring is generally best suited for businesses that invoice other businesses or government entities after providing products or services.

Improve Cash Flow Without Adding More Debt

If delayed customer payments are limiting your business, not a lack of sales, invoice factoring may provide a smarter way to strengthen cash flow. Rather than waiting weeks or months for payment or taking on another traditional loan, you can convert outstanding invoices into immediate working capital to help fund payroll, purchase inventory, take on larger opportunities, and continue growing with confidence. At AmeriFactors, we've helped businesses improve cash flow for more than 35 years by providing flexible invoice factoring solutions backed by exceptional service and the strength of Gulf Coast Bank & Trust Company.

Ready to improve your cash flow without taking on more debt? Contact AmeriFactors today for a complimentary consultation and discover how your accounts receivable can become one of your most valuable financial assets.

Terms and conditions apply. Services offered by AmeriFactors® Financial Group, LLC

Important Notice: The information provided in this article is for general informational purposes only and should not be considered accounting, tax, legal, or financial advice. Businesses should consult with their CPA, attorney, or other qualified professional regarding their specific circumstances and the appropriate accounting, tax, legal, or financial treatment.
Commercial Loan Brokers: Your Competitive Advantage for Faster Funding

In the commercial finance world, speed matters.

Every day, commercial loan brokers lose deals because traditional lenders move too slowly, require too much documentation, or simply don't understand unique business situations. While banks and conventional lenders can be excellent options for some borrowers, many business owners need funding now, not weeks from now.

That's why successful commercial loan brokers know exactly who to call when a deal needs to move fast.

AmeriFactors is the funding partner brokers call when timing is critical, the borrower doesn't fit traditional lending guidelines, and commission opportunities are on the line.

Why Commercial Loan Brokers Lose Deals

The average business owner seeking financing is often facing a time-sensitive situation:

When brokers send these deals through conventional lending channels, they often encounter:

The result? The borrower gets frustrated, looks elsewhere, or abandons the funding process altogether.

The AmeriFactors Difference: Built to Get to Yes

At AmeriFactors, we understand that every day a deal sits idle is a day your client isn't funded and you aren't earning a commission.

That's why our team is built around one simple principle: Get to yes quickly whenever possible.

Unlike traditional lenders, we focus on the strength of a company's receivables and business operations rather than relying solely on conventional lending metrics.

This allows us to help businesses that may not fit inside a bank's lending box.

Financing Solutions for Commercial Loan Brokers

Invoice Factoring

Businesses with outstanding invoices can turn their accounts receivable into immediate working capital instead of waiting 30, 60, or 90 days for payment.

Accounts Receivable Financing

Flexible funding solutions that help businesses maintain cash flow while continuing to grow.

Growth Capital

Funding that supports expansion opportunities, hiring initiatives, inventory purchases, and contract fulfillment.

Alternative Financing Solutions

When traditional financing isn't the right fit, AmeriFactors can often provide options that keep deals moving forward.

Why Brokers Choose AmeriFactors

Fast Decisions

We know your reputation depends on delivering solutions quickly. Our team works to evaluate opportunities efficiently so your clients get answers faster.

Transparent Communication

Brokers shouldn't have to chase updates.

We keep referral partners informed throughout the process, providing visibility from submission through funding.

Flexible Underwriting

Every business has a story. We take the time to understand the opportunity rather than relying on a rigid checklist.

Dedicated Partnership

Our broker relationships are built for the long term. When you bring a deal to AmeriFactors, you're working with a team committed to helping both you and your client succeed.

When Should Commercial Loan Brokers Contact AmeriFactors?

Close More Deals and Earn More Commissions

Commercial loan brokers succeed by finding solutions. When traditional lending channels slow down a deal, AmeriFactors can provide flexible financing options that help clients access working capital faster. Making AmeriFactors your first call can help you close more deals, strengthen client relationships, and increase commission opportunities.

Terms and conditions apply. Services offered by AmeriFactors® Financial Group, LLC, a wholly owned subsidiary of Gulf Coast Bank & Trust Co.

Summer temperatures aren’t the only thing rising this time of year. Late customer payments can create cash flow pressure. AmeriFactors helps businesses access working capital tied up in outstanding invoices, providing funds while customers pay on their terms. Don’t let payment delays turn up the heat on your business this summer.

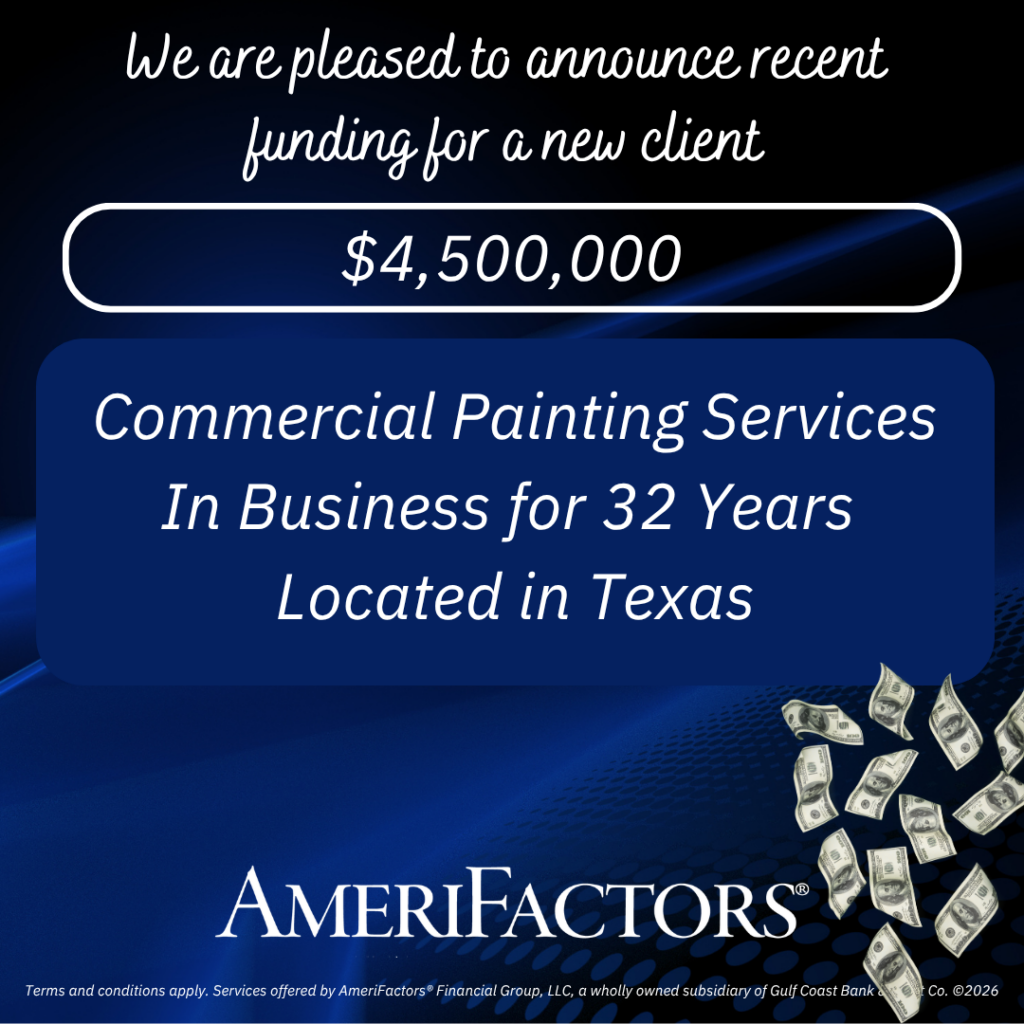
AmeriFactors recently funded $4,500,000 for a commercial painting company located in Texas. We help businesses access reliable funding solutions that support daily operations, payroll, and long-term growth opportunities. Contact us today to learn how AmeriFactors can support your business growth.

Non-Recourse vs. Recourse Factoring: Understanding the Difference and Choosing the Right Solution with AmeriFactors

AmeriFactors helps businesses improve cash flow and reduce credit risk through non-recourse factoring.

Non-Recourse vs. Recourse Factoring: What Every Business Should Know

Businesses waiting 30, 60, or even 90 days for customers to pay can create significant pressure on payroll, inventory purchases, job continuity, and day-to-day operations.

Invoice factoring provides immediate access to working capital by converting unpaid invoices into cash. However, not all factoring solutions are the same. One of the most important distinctions business owners should understand is the difference between non-recourse factoring and recourse factoring.

At AmeriFactors, we are recognized as a leader in non-recourse factoring, helping businesses improve cash flow while reducing credit risk.

What Is Invoice Factoring?

Invoice factoring is a financing solution where a business sells its outstanding accounts receivable to a factoring company in exchange for immediate cash.

Instead of waiting for customers to pay invoices, businesses can access funds quickly to:

Factoring is not a loan. It is a working capital solution that monetizes the value of your receivables.

What Is Recourse Factoring?

With recourse factoring, the business remains responsible if a customer fails to pay an invoice. If an invoice becomes uncollectible after a specified period, the factoring company can require the business to repurchase the invoice. The business retains the risk of customer non-payment which includes potential unexpected chargebacks that impact cash flow and higher exposure during economic uncertainty. Recourse factoring can be a practical option when customer payment histories are highly predictable, but it does not provide protection against customer insolvency.

What Is Non-Recourse Factoring?

With non-recourse factoring, the factoring company assumes the credit risk if an approved customer becomes insolvent or unable to pay due to financial reasons. For example, if a customer files bankruptcy after an invoice has been purchased by a non-recourse factor like AmeriFactors, the non-recourse arrangement may protect the business from having to buy back that invoice.

This provides businesses with an added layer of protection that traditional recourse factoring does not offer.

Benefits of Non-Recourse Factoring

For many businesses, non-recourse factoring offers more than immediate access to working capital. It can also provide protection against losses if an approved customer files for bankruptcy, while supporting key back-office functions such as invoicing, collections, and accounts receivable management to help accelerate payments and improve cash flow.

Recourse vs. Non-Recourse Factoring: Key Differences

FeatureRecourse FactoringNon-Recourse Factoring
Customer Credit RiskBusiness Retains RiskFactor Assumes Covered Credit Risk
Protection Against InsolvencyNoYes
Cash Flow PredictabilityModerateHigher
Cashflow Risk Management BenefitsLimitedSignificant

The primary difference comes down to who bears the risk when a customer cannot pay due to a covered credit event.

Why Businesses Choose Non-Recourse Factoring

In today's business environment, customer financial stability can change quickly. A single large customer bankruptcy can create serious cash flow challenges for suppliers.

Businesses often choose non-recourse factoring because it helps:

Why AmeriFactors Is a Leader in Non-Recourse Factoring

For decades, AmeriFactors Financial Group has helped businesses unlock working capital and manage risk through customized factoring solutions.

As a leading provider of non-recourse factoring, AmeriFactors offers:

Industry Expertise

Our team understands the unique challenges faced by most industries that rely on cash flow.

Personalized Service

Every business is different. AmeriFactors works closely with clients to develop factoring solutions that align with their goals, customers, and industry requirements.

Credit Protection

AmeriFactors' non-recourse factoring programs help safeguard businesses from customer credit risk, providing added financial security and peace of mind. We can also provide valuable credit insights on prospective customers, helping businesses make informed decisions before extending credit or entering into a new business relationship.

Fast Access to Working Capital

Businesses can receive funding quickly, allowing them to meet payroll, purchase materials, and seize growth opportunities without waiting for customer payments.

Strong Reputation and Stability

With decades of experience and thousands of businesses served, AmeriFactors has built a reputation as a trusted financial partner committed to helping companies grow.

Is Non-Recourse Factoring Right for Your Business?

Non-recourse factoring may be an ideal solution if your business:

The right factoring solution depends on your business objectives, customer portfolio, and risk tolerance.

Get Started with AmeriFactors

If you're evaluating non-recourse factoring versus recourse factoring, it's important to work with a partner that understands both cash flow management and credit risk protection.

AmeriFactors combines flexible funding solutions, industry expertise, and non-recourse options designed to help businesses grow with confidence.

Contact AmeriFactors today to learn how non-recourse factoring can improve your cash flow, protect your business, and support your long-term success.

Frequently Asked Questions

What is the main difference between recourse and non-recourse factoring?

The primary difference is who assumes the risk if an approved customer doesn’t pay for financial reasons or becomes insolvent. In recourse factoring, the business retains that risk. In non-recourse factoring, the factoring company assumes covered credit risk.

Is invoice factoring considered debt?

No. Factoring is not a loan. It is the sale of accounts receivable for immediate cash.

Why do businesses choose AmeriFactors for non-recourse factoring?

Businesses choose AmeriFactors for its experience, flexible funding solutions, personalized service, and leadership in non-recourse factoring programs.

Terms and conditions apply. Services offered by AmeriFactors® Financial Group, LLC, a wholly owned subsidiary of Gulf Coast Bank & Trust Co.

AmeriFactors: Solutions Built for Your Business Success

AmeriFactors provides flexible funding and cash flow solutions for growing businesses.

In today’s fast-moving business environment, access to working capital and efficient financial solutions can make the difference between growth and stagnation. AmeriFactors Financial Group, LLC provides flexible, scalable funding and support services designed to help businesses improve cash flow, reduce risk, and accelerate success.

What Does AmeriFactors Do?

AmeriFactors specializes in invoice factoring, payroll funding, and back-office solutions. These services are designed to help businesses unlock capital tied up in unpaid invoices and streamline financial operations.

At its core, AmeriFactors helps companies:

Invoice Factoring: Turn Receivables into Immediate Cash

One of AmeriFactors’ primary services is invoice factoring, a financing solution that converts unpaid invoices into immediate working capital.

How It Works

1. You provide goods or services to your customer
2. You submit your invoice to AmeriFactors
3. AmeriFactors advances up to 98% of the invoice value
4. Once your customer pays, you receive the remaining balance minus a small fee

Benefits of Invoice Factoring

• Fast access to cash, often within 4 hours
• No new debt added to your balance sheet
• Credit support and collections handled for you
• Scalable funding as your business grows

Payroll Funding: Keep Your Workforce Paid Without Stress

Meeting payroll can be one of the biggest challenges for staffing companies and labor-intensive businesses. AmeriFactors offers payroll funding solutions to help that your employees are paid on time, even when customers haven’t paid yet.

Why It Matters:

Eliminate payroll timing gaps

Back-Office Support: Focus on What You Do Best

AmeriFactors goes beyond funding by offering back-office services, including:

• Accounts receivable management
• Credit checks and risk analysis
• Invoice processing and collections

This allows business owners to spend less time on administrative tasks and more time on revenue-generating activities.

Industries AmeriFactors Serves

AmeriFactors supports a wide range of industries, including but not limited to:

Each solution is customized to meet the specific challenges of your industry and your business.

Why Choose AmeriFactors?

AmeriFactors stands out by combining financial expertise with personalized service. Their approach is not one-size-fits-all — they build solutions around your business goals.

What Sets AmeriFactors Apart:

• Fast funding and streamlined onboarding
• High advance rates depending on the industry and terms
• Dedicated account management
• Non-recourse funding
• Decades of industry experience

Built for Your Business Success

At every stage of your business journey, having the right financial partner matters. AmeriFactors provides the tools, capital, and support needed to help you navigate challenges and seize new opportunities. If your business is experiencing cash flow gaps, rapid growth, or operational strain, AmeriFactors offers solutions designed to keep you moving forward.

Frequently Asked Questions

How fast can AmeriFactors provide funding?

Funding may be available quickly, often within 4 hours, depending on approval, terms, and conditions.

Is invoice factoring a loan?

Invoice factoring is not traditional debt. It converts eligible unpaid invoices into working capital.

What industries does AmeriFactors serve?

AmeriFactors serves most industries including staffing, recruiting, telecom, utilities, manufacturing, oil and gas, government contracting, and service-based businesses.

Ready to Improve Your Cash Flow?

Explore how AmeriFactors can support your business with customized funding and financial solutions. With faster access to capital and expert support, you can focus on what matters most — growing your business.

Terms and conditions apply. Services offered by AmeriFactors® Financial Group, LLC, a wholly owned subsidiary of Gulf Coast Bank & Trust Co.

Invoice Factoring FAQs: How It Works, Rates, and Advantages

Frequently Asked Questions About Invoice Factoring

What Is Invoice Factoring and How Does It Work?

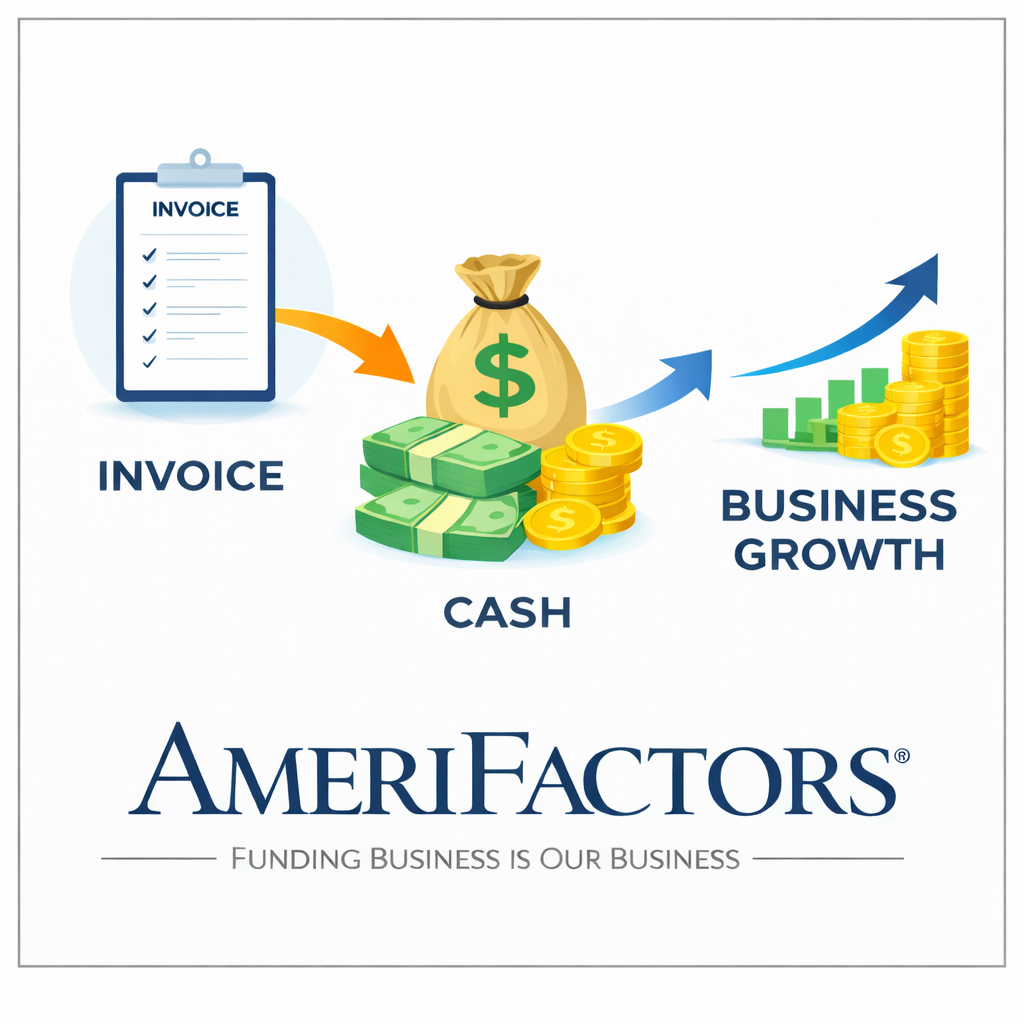
Invoice factoring, also known as accounts receivable financing, allows businesses to sell unpaid invoices to a factoring company in exchange for immediate cash. Instead of waiting 30, 60, or 90 days for customers to pay, businesses can improve cash flow quickly. With AmeriFactors, businesses receive fast funding while AmeriFactors professionally manages the accounts receivable process, helping companies stay focused on operations and growth.

Diagram showing the invoice factoring process where a business turns an invoice into cash and uses it to drive business growth

What Are the Advantages of Invoice Factoring?

The AmeriFactors advantage provides businesses with:

Invoice factoring is commonly used in industries such as staffing, manufacturing, distribution, wireless, utilities, construction, and service-based businesses. These industries rely on consistent cash flow to cover payroll, inventory, and operating expenses. AmeriFactors makes factoring simple, reliable, and relationship-friendly by combining fast funding with back-office receivables support.

Who Is Invoice Factoring Best For?

Invoice factoring with AmeriFactors is ideal for businesses that offer payment terms to customers and need faster access to cash flow. It is especially helpful for growing companies, startups, companies in distress, or organizations experiencing delayed customer payments. Because approval is based on a customer’s creditworthiness rather than the business owner’s credit, factoring is also a strong option for businesses with limited or unfavorable credit history.

What Is Invoice Factoring in Simple Terms?

In simple terms, invoice factoring is when a business sells its unpaid invoices to a factoring company like AmeriFactors to get cash right away instead of waiting for customers to pay.

How Does Invoice Factoring Work With AmeriFactors?

Invoice factoring with AmeriFactors follows a simple process:

  1. Your business delivers a product or service and issues an invoice
  2. You submit the invoice to AmeriFactors for funding
  3. In as little as 4 hours, AmeriFactors advances up to 95% of the invoice value
  4. Your customer submits payment directly to AmeriFactors
  5. AmeriFactors releases the remaining balance to you, minus the factoring fee

This process helps businesses maintain steady cash flow without waiting on slow-paying customers.

How Fast Do You Get Paid With Invoice Factoring?

AmeriFactors funds clients in as little as 4 hours after approval, making invoice factoring one of the fastest working capital solutions available.

Do I Need Good Credit to Qualify for Invoice Factoring?

No. Good credit is not required for AmeriFactors invoice factoring. Approval is based on your customer’s ability to pay, not your business credit score. This makes factoring an excellent solution for growing businesses or companies with challenged credit.

How Much Does Invoice Factoring Cost?

Factoring fees vary based on items such as invoice volume, customer payment terms, and the industry of the business. AmeriFactors rates can be as low as 1% per invoice, and many businesses find factoring more affordable than late fees, missed opportunities, or high-interest loans.

Is Invoice Factoring Better Than a Business Loan?

Invoice factoring can be a better alternative to a traditional business loan because:

AmeriFactors provides a flexible financing solution based on sales and receivables, not borrowing.

Does AmeriFactors Help With Accounts Receivable Management?

Yes. In addition to providing fast funding, AmeriFactors supports accounts receivable management and payment follow-up, reducing administrative workload and improving overall cash flow efficiency.

Is the AmeriFactors Approval Process Quick and Easy?

Yes. The AmeriFactors invoice factoring approval process is quick and easy, with minimal paperwork and fast turnaround. Many businesses can be approved and funded in as little as one business day.

Get Started With AmeriFactors Invoice Factoring

If your business is ready to improve cash flow, reduce receivables stress, and get paid faster, AmeriFactors invoice factoring can help. With fast approval, advances up to 95%, rates as low as 1% per invoice, and accounts receivable support, AmeriFactors is a trusted partner for businesses seeking reliable working capital solutions.

Terms and conditions apply. Services offered by AmeriFactors® Financial Group, LLC